Paul “Paolo” Mozzicato is a commercial risk advisor and principal at Smith Brothers Insurance in Glastonbury, Connecticut, where he has helped clients identify and manage complex business risks since 2018. Licensed as a life, health, property, and casualty producer with Series 63, 65, and 7 qualifications, Mozzicato focuses on construction, real estate, transportation, and manufacturing clients, designing commercial solutions that span workers’ compensation, fleet auto, disability, and key person life insurance. He balances that work with his role as principal and project manager at Mozzicato Real Estate in Hartford, where he oversees commercial and residential properties, and his earlier two decades as principal of Mozzicato Bakery. A founding member of the South Hartford Business Alliance, Mozzicato holds a master’s degree in economics from Trinity College, a real estate degree from the University of Hartford, and a bachelor’s degree in economics from Boston University, and has been named among Hartford Business Journal’s 40 Under 40 and 50 Most Influential People.
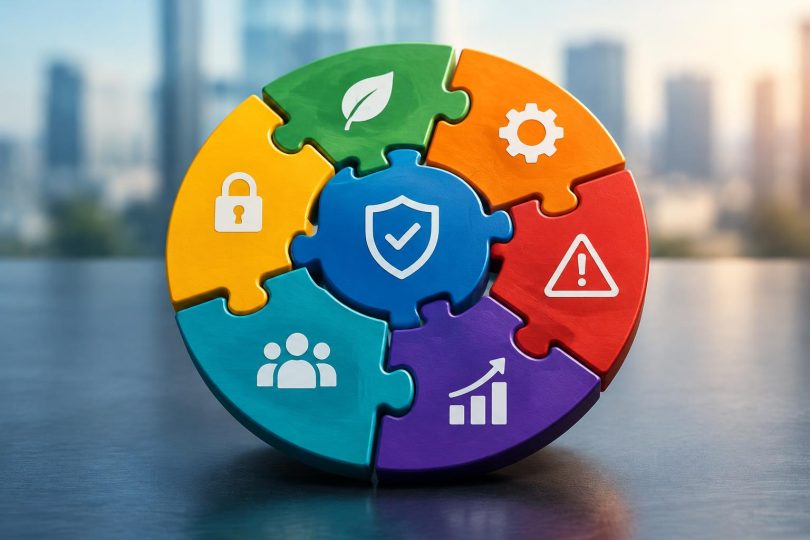
Insurance is an important part of protecting an organization from financial losses, but purchasing a policy should be only one step in a broader risk-management process. Enterprise risk management considers how risks could affect an organization’s objectives and brings those considerations into strategic decision-making. Within that framework, insurance becomes one tool for addressing exposures rather than the entire risk strategy.
The process begins with understanding what could go wrong. Organizations need to identify exposures across their operations and consider both the likelihood of an event and its potential financial or operational consequences. A new facility, technology system, supplier relationship, geographic market, or contractual obligation can introduce risks that were not present when an insurance program was originally designed.
Once exposures are identified, leadership can consider the organization’s risk appetite and how much risk it is prepared to retain. Some losses may be manageable within existing resources, while others could threaten financial stability or disrupt critical operations. Insurance can transfer part of that financial exposure and provide resources following a covered loss, but deductibles, limits, exclusions, and policy conditions can leave some risk with the organization.
Risk controls should also be considered alongside insurance. An organization might reduce exposure through stronger internal controls, physical safeguards, cybersecurity measures, or business continuity planning.
These measures can reduce the likelihood or severity of a loss, while insurance can provide financial protection when an adverse event still occurs. Risk management guidance recognizes control, retention, avoidance, and transfer as techniques that can be used together rather than as mutually exclusive choices.
This integrated approach becomes particularly important as organizations change. A company that expands into a new market or takes on new contractual obligations may develop exposures that its existing insurance program does not fully address. Reviewing insurance alongside operational and strategic changes can help identify gaps before a loss exposes them.
Coordination among risk, finance, legal, and operational leaders can be especially valuable when contractual responsibilities and insurance coverage intersect. Insurance also should be evaluated in the context of organizational resilience.
Recovery plans, emergency procedures, and continuity strategies address how an organization will respond when disruption occurs. Insurance can support that recovery by providing funds for covered losses, but financial recovery is only one component of restoring operations.
Effective resilience planning considers both the measures that reduce disruption and the resources available afterward. A strategic insurance review therefore asks broader questions than whether the organization has adequate coverage.
What risks are being retained intentionally? Which exposures can be reduced through stronger controls? Where does risk transfer make financial sense? How have the organization’s operations and risk profile changed since the last review?
Treating insurance as part of enterprise risk strategy gives leadership a more complete view of the organization’s exposure. Rather than approaching coverage as a standalone purchase, decision-makers can evaluate insurance alongside prevention, mitigation, retention, and resilience.
Regularly revisiting those choices can help ensure that the organization’s risk strategy keeps pace with changes in its operations, financial position, and external environment. That perspective can support more deliberate decisions about protecting assets, managing uncertainty, and pursuing strategic objectives.
About Paul “Paolo” Mozzicato
Paul “Paolo” Mozzicato is a commercial risk advisor and principal at Smith Brothers Insurance in Glastonbury, Connecticut, where he has worked with clients across construction, real estate, transportation, and manufacturing since 2018. He also serves as principal of Mozzicato Real Estate in Hartford and previously led Mozzicato Bakery for nearly two decades. A founding member of the South Hartford Business Alliance, he holds degrees in economics from Boston University and Trinity College and has earned recognition among Hartford Business Journal’s 40 Under 40 and 50 Most Influential People.